Why payments deserve a place in your international expansion plan
By Nicola EWN • Published: 20 Nov 2026 • 16:05 • 3 minutes read
Credit:earthphotostock/Shutterstock.com
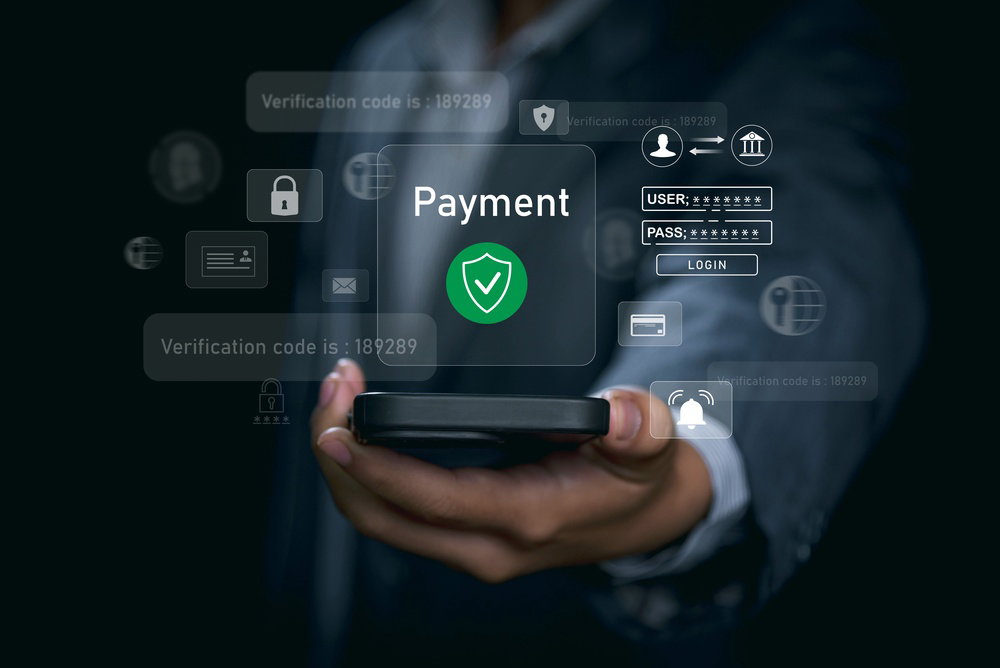
When a business enters a new market, the usual checklist covers product localisation, marketing, and logistics. Payments often get less attention, even though they directly affect whether a visitor becomes a paying customer. A weak payment setup can lead to abandoned carts, declined transactions, and poor conversion in new regions. A well-planned one supports growth instead.
Local payment methods build trust
Customers expect to see the payment options they use every day. If those options are missing at checkout, many will simply leave.
In mature markets, cards remain the default for many shoppers, alongside digital wallets such as Apple Pay and Google Pay and bank-to-bank transfers. In many emerging markets, local solutions dominate: Alipay and WeChat Pay in China, M-Pesa in Kenya, and Pix in Brazil. Sometimes this is a matter of habit, as with cash-based options like OXXO in Mexico. In other regions it reflects limited card penetration, as in parts of Sub-Saharan Africa, where mobile money is often easier to access than a bank card.
Local acquiring can reduce false declines
Issuing banks often treat cross-border transactions as higher risk. Consider a German customer buying from a UK store that uses a UK acquirer. The German bank sees a foreign acquiring bank in the request, which can act as an extra risk signal and lead to stricter checks or a refusal. Processing payments through a local acquirer can lower that friction and may improve approval rates.
Multi-currency support helps control costs
International payments frequently involve foreign exchange markups and cross-border network fees, which eat into margins, especially at high volumes. Multi-currency settlement lets a business hold funds in the currencies it receives rather than converting everything into one, which can reduce conversion costs.
Currency matters to customers as well. Shoppers prefer to see prices in a familiar currency and dislike discovering a different final amount at checkout. Multi-currency processing addresses this, although conversion fees may still apply depending on the setup.
Fraud prevention needs to adapt to each region
Expanding into new countries exposes merchants to unfamiliar fraud patterns and a higher risk of chargebacks. Rules that work well at home may not suit other markets, because local payment behaviour and scam techniques differ. Tightening filters too far increases false declines, while loosening them can push chargeback rates up and, in some cases, lead to penalties from card networks.
Many merchants now use AI-based tools that analyse behaviour, detect patterns across large datasets, and adjust risk scores dynamically. This can help catch fraud in new markets without adding unnecessary friction for genuine customers.
Key steps for building an international payment strategy
- Research payment preferences. Identify the most popular methods in each target market and add them to checkout.
- Localise the checkout. Let customers pay in their own currency and view the page in their own language.
- Optimise for mobile. The payment flow should be quick and smooth on smartphones, particularly in mobile-first markets.
- Understand local regulations. Follow data privacy laws and security standards in each country to avoid penalties and keep customer trust.
- Use the right infrastructure. Handling many countries, currencies, and payment methods in-house is difficult, which is why many merchants rely on a payment service provider (PSP).
The role of payment service providers
Businesses that sell across borders rarely build all of this from scratch. Global payment service providers typically offer ready-made infrastructure covering payment method integration, settlement and payouts, fraud tools, and dashboards for tracking performance and generating reports. This lets smaller teams enter several markets without separate technical integrations in each one.
Support levels vary widely between providers. Some offer only help-centre articles and chatbots, while others assign dedicated account managers. During rapid scaling, access to a real person who can resolve issues quickly can prevent costly delays.
Final thoughts
Expanding abroad is complicated enough without payment problems getting in the way. By matching payment methods, currencies, and security measures to each market, businesses can remove friction at checkout and turn payments into a genuine driver of international growth.
This article is for informational purposes only and does not constitute financial, legal or business advice. Payment providers vary in the services they offer and the regulation they are subject to. Always check a provider’s licensing and terms, and seek independent professional advice, before choosing a payment partner.
Follow Euro Weekly News on Google News
Get breaking news from Spain, travel updates, and expat stories directly on your Google News feed.
Follow on Google NewsSign up for personalised news
Subscribe to our Euro Weekly News alerts to get the latest stories into your inbox!
By signing up, you will create a Euro Weekly News account if you don't already have one. Review our Privacy Policy for more information about our privacy practices.
Nicola EWN
Nicola is a member of the editorial team specialising in features, digital content and online publishing. With broad experience across media and communications, she works across feature articles, editorial content and digital platforms, managing content across a range of subjects.
Comments