Spain tax warning: Four-cent error brings about call for fairer fines
By Adam Woodward • Updated: 24 Oct 2026 • 9:53 • 3 minutes read
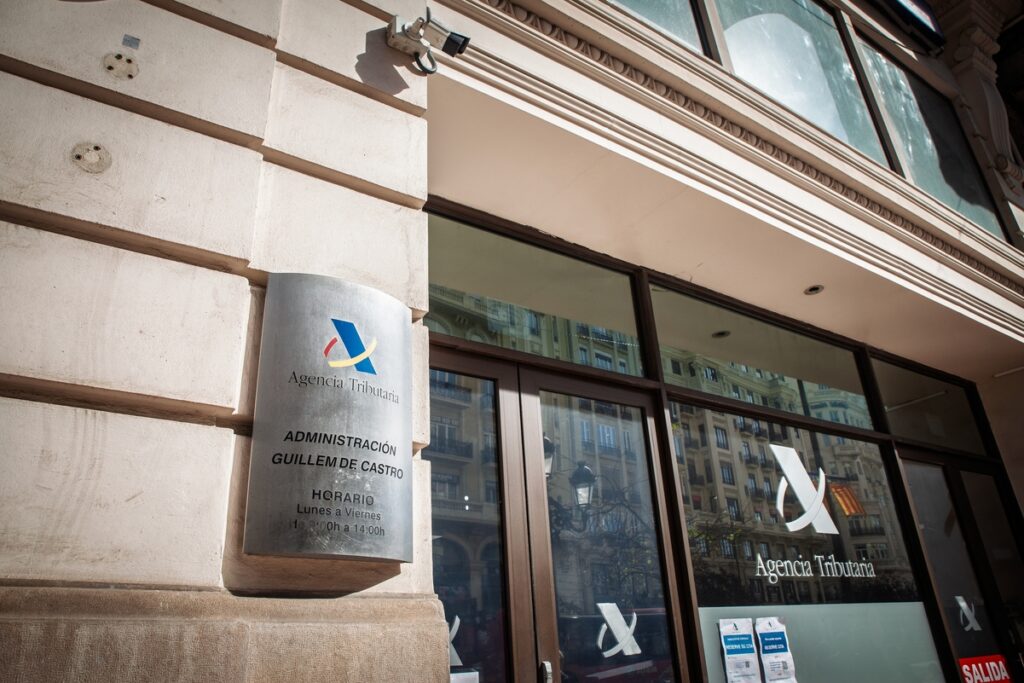
The dreaded tax office. Credit: BalkansCat - Shutterstock
A tiny payment error has caused calls for changes to Spain’s tax rules after a taxpayer faced a hefty surcharge because a payment to the Tax Agency fell just four cents short of the amount owed.
The case has been examined by the Consejo para la Defensa del Contribuyente (Council for the Defence of Taxpayers), an advisory body attached to Spain’s Ministry of Finance. In its 2025 annual report, the council argues that the consequences of such a small mistake can be wildly disproportionate and recommends changes to how certain tax debts are handled.
Why did four cents cause such a problem?
The case involved Modelo 111, the tax form used by businesses and self-employed workers to declare income tax withheld from employees and other recipients. The taxpayer had declared a debt for the third quarter of 2023 but failed to pay it within the original deadline or request a payment extension or installment arrangement. Once the voluntary payment period expired, the debt entered the enforcement stage under Spain’s General Tax Law.
The taxpayer subsequently paid almost the entire amount before receiving formal notification of the enforcement order. However, a small error when entering the payment left four cents outstanding. Under the existing rules, the more favourable 5 per cent executive surcharge applies only when the entire outstanding debt has been paid before the enforcement order is notified.
Because the payment was slightly incomplete, the Tax Agency proceeded with an enforcement order covering the debt. The council acknowledged that the collection authority had applied the legislation as written. Its objection was that the rules left little room to account for an obvious, insignificant error, despite the much larger financial consequences.
Importantly, the original payment deadline had already been missed. The four-cent mistake did not cause the initial late-payment surcharge; it prevented the taxpayer from qualifying for the more favourable rate.
Calls for a ‘right to make a mistake’
The council has recommended that the Ministry of Finance and the Tax Agency introduce consistent proportionality criteria for enforcement surcharges when only a very small amount remains unpaid because of an obvious arithmetic or typing error.
It wants the authorities to consider whether the outstanding sum is genuinely insignificant and whether the taxpayer can demonstrate that the shortfall resulted from a mistake. The proposal includes extending protections to certain errors involving amounts below €3, creating what the council describes as a form of ‘right to make a mistake’ when paying tax debts.
The €3 threshold is not entirely new. A joint resolution issued in November 2022 provided for the cancellation of certain outstanding debts below that amount where the cost of collecting them could outweigh the money recovered. The council argues that a comparable approach should be considered when a taxpayer has paid almost all a debt but made a minor error in the amount transferred.
It has also called for a broader review of Spain’s enforcement surcharge system, including the differences between taxpayers who submit their declarations on time but fail to pay and those who submit them late without first receiving a demand from the authorities.
What does this mean for foreign residents in Spain?
The case is a reminder that meeting a tax deadline and paying the correct amount are two separate requirements. British residents and other foreign nationals with tax obligations in Spain are subject to the applicable Spanish tax rules, just like other taxpayers in comparable circumstances.
Anyone paying a tax bill should check the amount carefully, ensure the payment has gone through and confirm that the full balance has been covered. If a payment is short, even by a small amount, it is worth seeking advice promptly rather than assuming the difference is too minor to matter.
Anyone who receives an enforcement notice should also check the deadline for responding and paying, as the surcharge can depend on whether the conditions for a reduced rate are met.
The council’s recommendations do not automatically change the law. Its annual report does not establish that the surcharge in this case has been cancelled, nor does it confirm that the proposed protections have been adopted.
For now, the case raises a straightforward question for Spain’s tax authorities: should an obvious mistake involving a few cents carry such serious financial consequences when a taxpayer has paid virtually the entire debt?
Follow Euro Weekly News on Google News
Get breaking news from Spain, travel updates, and expat stories directly on your Google News feed.
Follow on Google NewsSign up for personalised news
Subscribe to our Euro Weekly News alerts to get the latest stories into your inbox!
By signing up, you will create a Euro Weekly News account if you don't already have one. Review our Privacy Policy for more information about our privacy practices.
Adam Woodward
Adam is a writer who has lived in Spain for over 25 years. With a background in English teaching and a passion for music, food, and the arts, he brings a rich personal perspective to his work at Euro Weekly News. As a father of three with deep roots in Spanish life, Adam writes engaging stories that explore culture, lifestyle, and the everyday experiences that shape communities across Spain.
Comments